Kansas City · Independence · Lee’s Summit
Kansas City Metro
Spring hail tracks across Jackson, Clay and Cass counties, landing on brick bungalows in Brookside and new HOA subdivisions alike.
Independent property claim appraisal · Statewide
Hail, tornado, ice and sinkhole claims across the state get accepted and then underpaid. A Missouri Insurance Appraiser measures the damage, prices it independently and carries the dispute through the appraisal clause already written into your policy.
Why owners call
Most underpaid claims in Missouri aren’t denied. They’re short: a missed slope on a hail-hit roof, gutters left off, siding that can’t be matched, or a code upgrade nobody priced.
The insurer’s adjuster writes one estimate. When yours says something different, you need more than an argument; you need an itemized valuation that stands up when someone checks it. That is the job of a Missouri Insurance Appraiser. We build the number from our own inspection and measurements, then use the appraisal clause to get it in front of a panel that can settle it.
Not sure which side of the line you’re on? A Missouri Insurance Appraiser will tell you on the first call, including when the honest answer is a supplement request or a lawyer.
How our firm worksAppraisal help
Every service comes back to one question: what does it honestly cost to put this property back? Start with an estimate review, or bring us in once appraisal has been demanded.
 01
 02
 03
 04
 05
 06
 07
 08
 09
 10
 11
Missouri’s claim calendar
Each row shows how often a peril tends to drive claims through the year. A Missouri Insurance Appraiser sees spring hail and tornado files first, ice and frozen-pipe files in winter, and wind from summer storm complexes in between.
The process
The appraisal clause turns an open-ended argument into a defined process with a binding result. Here are the five steps, start to finish.
Read the full roadmapSend the insurer’s estimate and your photos. A Missouri Insurance Appraiser reviews the policy and tells you honestly whether appraisal makes sense.
We inspect, measure and write an independent line-item estimate priced for your part of Missouri, not a markup of the insurer’s.
If the gap is worth it, appraisal is invoked under your policy’s clause and we’re named as your appraiser within its time limit.
We go item by item with the insurer’s appraiser. Most disagreements shrink here, once both sides see the same evidence.
Anything left goes to a neutral umpire. Two signatures out of three set the amount of loss, and payment follows the policy’s terms.
Statewide
Brick flats in St. Louis, HOA roofs in Lee’s Summit, sinkholes near Springfield and river towns in the Bootheel. A Missouri Insurance Appraiser has to know how each region’s weather shows up in an estimate.
Spring hail tracks across Jackson, Clay and Cass counties, landing on brick bungalows in Brookside and new HOA subdivisions alike.
Old brick flats and slate roofs in the city, ranch homes in the county, and river-bottom flood history in Chesterfield Valley.
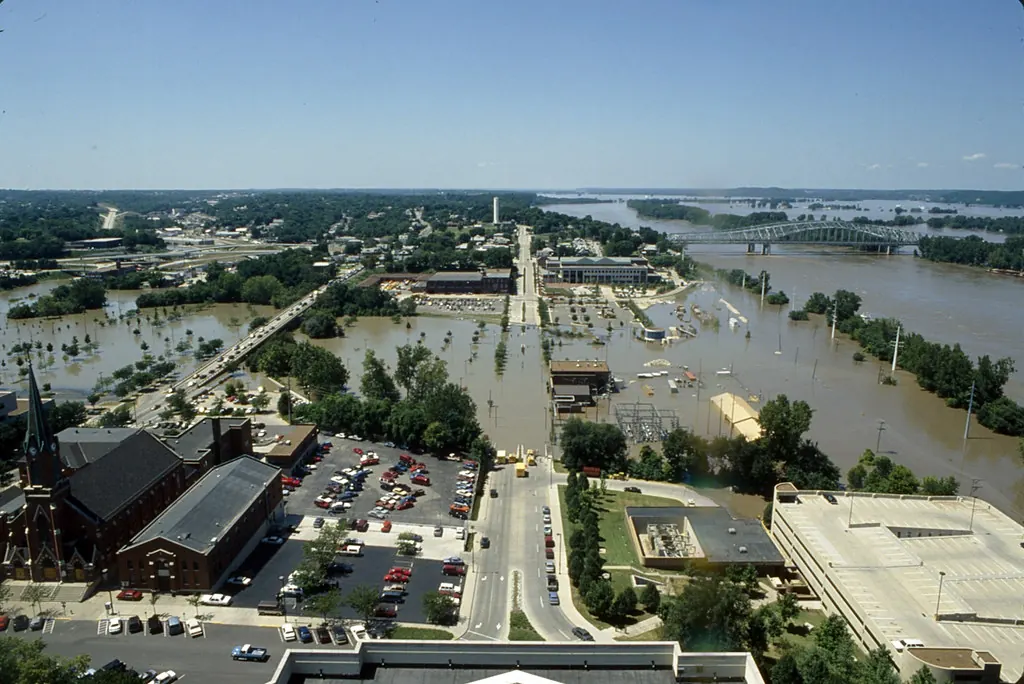
Tornadoes, Missouri River flooding and hail over university housing and older capital-city neighborhoods.
Karst ground with thousands of mapped sinkholes, ice storms like January 2007, and wooded lots where limbs meet roofs.
Tornado Alley’s eastern edge. Rebuilding after 2011 shaped how this corner of the state thinks about code upgrades.
Missouri and Mississippi river towns with farm buildings, historic brick downtowns and New Madrid earthquake questions.
Storm history
These events shaped how insurers, contractors and owners in Missouri handle claims today. Every Missouri Insurance Appraiser file is a smaller version of the same story: damage, an estimate, and a question about what it really costs.
A series of major quakes centered in the Bootheel; the seismic zone is why earthquake coverage comes up in southeast Missouri.
Missouri and Mississippi river flooding reached homes and businesses from St. Joseph to St. Charles County and Cape Girardeau.
An April storm along the I-70 corridor in the St. Louis area became one of the costliest hail events of its time.
July windstorms brought down trees and lines across the St. Louis area and left many without power for days.
Freezing rain coated southwest Missouri, including Springfield, snapping limbs onto roofs and cars.
On May 22 an EF5 tornado cut across Joplin, one of the most destructive tornadoes in U.S. history.
An EF3 tornado struck the capital city on May 22, eight years to the day after Joplin, as river flooding built nearby.
A rare December outbreak included a tornado in the Defiance area of St. Charles County.
Quick check
Type in the two estimates you already have. If the difference is large, it’s worth a conversation with a Missouri Insurance Appraiser. If it’s small, a documented supplement request may close it faster and for less.
The full award & net payout estimator also subtracts the deductible, checks already paid and appraisal fees.
Two-number gap check
Illustrative · no sign-up
of the disputed amount
Toolkit
Check the math before you pick up the phone. Every tool runs in your browser, and nothing you type is stored or sent.
 Estimator
 CalculatorCalculator
 Calculator
 PlannerChecklist
 Estimator
Communities
We cover the whole state. These twelve communities each have a page on local storms, housing and neighborhoods.
 Jackson County
 Independent city
 Greene County
 Boone County
 Jackson County
 Jackson County
 St. Charles CountyBuchanan County
 Jasper County
 Cole County
 Cape Girardeau County
 St. Louis County
Questions
Short answers to what people ask first. There are more in questions answered.
No cost for the first conversation. We’ll tell you plainly whether appraisal fits.
(844) 537-1427Send claim detailsMon–Fri, 8am–6pm CTWe value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appraiser we inspect, write an independent line-item estimate, work with the insurer’s appraiser and, if needed, present open items to a neutral umpire.
No. A public adjuster handles and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question, the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When coverage has been accepted, you have the insurer’s itemized estimate, and the gap between it and a qualified contractor’s estimate is meaningful, often more than about 10% or several thousand dollars.
Generally no. Appraisal sets the amount of loss. Coverage disputes, denials and questions under Missouri’s vexatious refusal statutes are legal matters for a Missouri attorney.
Most clauses say each side pays its own appraiser and splits the umpire. We put our fee in writing before any work starts, and the first conversation is free.
Yes. We work in all 114 counties and the City of St. Louis, from the Kansas City metro to the Bootheel.
Field notes
Follow a typical appraisal clause from the written demand to the signed award, and learn which questions the panel can’t answer.
What to photograph after a Missouri hailstorm, why matching and cosmetic exclusions cause fights, and how percentage deductibles change the math.
Appraisal answers “how much?” Missouri’s vexatious refusal statutes raise a different, legal question. Here’s how to tell which one you’re facing.
Send the estimate and a few photos. If appraisal isn’t the right move, we’ll say so.